 by
Summary Box: PM SVANidhi provides collateral-free working-capital loans to eligible street vendors, with progressive credit up to ₹50,000. This guide explains the latest loan amounts, repayment periods, interest subsidy, digital cashback and application process.
What Is PM SVANidhi?
PM SVANidhi stands for Prime Minister Street Vendor’s AtmaNirbhar Nidhi. Launched in June 2020, the scheme provides formal working-capital credit to eligible street vendors. After its restructuring in 2025, the lending period was extended until March 31, 2030, with higher first and second loan limits and additional digital-credit features.
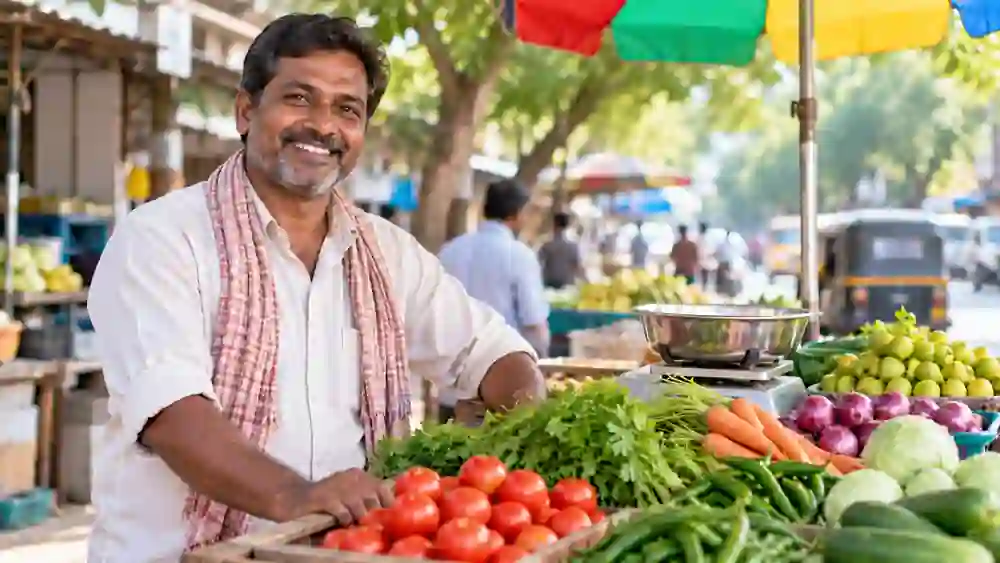
The scheme is designed for vendors selling goods or providing services in streets, footpaths, pavements and similar locations. Examples include vegetable and fruit sellers, food vendors, tea sellers, barbers, cobblers, laundry services and other small street businesses. Coverage is also being expanded beyond statutory towns to census towns, urban agglomerations and peri-urban areas in a graded manner.
PM SVANidhi Loan Amount and Repayment Period
The restructured scheme provides credit in three progressive stages:
- First loan: Up to ₹15,000 — repayment period up to 12 months
- Second loan: Up to ₹25,000 — repayment period up to 18 months
- Third loan: Up to ₹50,000 — repayment period up to 36 months
The higher loan stages are linked to repayment performance. The exact amount sanctioned depends on eligibility and the lending institution’s assessment.
7 Key Benefits of PM SVANidhi
1. Collateral-Free Working Capital
Table of Contents
Eligible vendors can access working-capital loans without traditional collateral. The facility is intended to help vendors purchase stock, maintain daily operations and strengthen their small businesses.
2. Progressive Loan Amounts
The three-stage structure allows eligible vendors to move from smaller working-capital support to larger credit after meeting repayment conditions.
3. 7% Interest Subsidy
Timely repayment can qualify the borrower for an interest subsidy of 7%, subject to the applicable scheme rules. This can reduce the effective cost of borrowing.
4. Digital Transaction Cashback
The restructured scheme provides cashback incentives for eligible digital retail and wholesale transactions. Vendors can receive cashback of up to ₹1,600, subject to the prescribed transaction conditions.
5. UPI-Linked RuPay Credit Card
Eligible vendors who successfully repay the second loan can receive a UPI-linked RuPay Credit Card with a credit limit of up to ₹30,000.
6. Credit Guarantee Support
The scheme includes credit-guarantee support intended to encourage participating lenders to provide loans to street vendors.
7. Wider Social and Business Support
Through SVANidhi se Samriddhi, beneficiaries can be connected with selected government welfare schemes covering areas such as insurance, pension, financial inclusion and other social-security benefits.
How to Apply for PM SVANidhi
Eligible vendors can approach participating banks and other lending institutions through the scheme’s application and verification process. The local Urban Local Body (ULB) plays an important role in identifying eligible vendors and mobilising applications.
Applicants should keep their identification, address and vending-related information ready. Requirements can vary according to the applicant’s circumstances and the lender’s process, so applicants should verify the current requirements before submitting an application.
Frequently Asked Questions
Who can get a PM SVANidhi loan?
The scheme is intended for eligible street vendors and hawkers engaged in vending goods or providing services to the public.
What is the maximum PM SVANidhi loan amount?
The third loan tranche provides up to ₹50,000, subject to eligibility and repayment conditions.
Is PM SVANidhi a collateral-free loan?
Yes. The scheme provides collateral-free working-capital loans to eligible street vendors.
What is the interest subsidy?
Eligible vendors can receive a 7% interest subsidy for timely repayment, according to scheme conditions.
Conclusion
PM SVANidhi gives eligible street vendors access to progressive working-capital credit, interest support and digital-payment incentives. With loan limits of up to ₹50,000 and the scheme extended through March 2030, vendors can check the current eligibility and application process through the official channels before applying.
Internal Link Suggestion:
PMMY: 6 Powerful Loan Options for Small Businesses
Official External Link(s):
PM SVANidhi Official Portal
Ministry of Housing and Urban Affairs – PM SVANidhi